Why This Coverage Detail Matters More Than Most Homeowners Realize
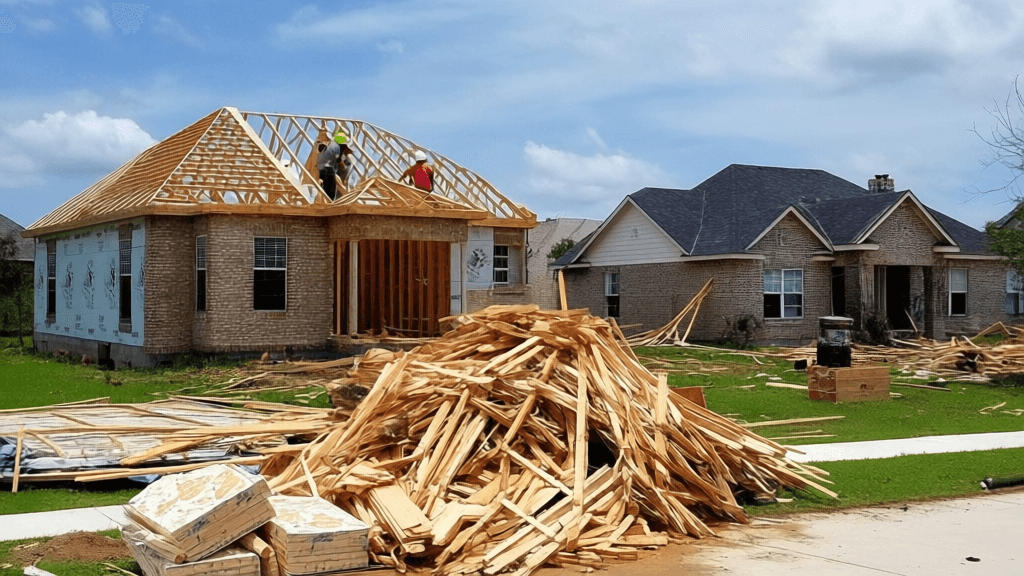
After a major storm in Beaumont, many homeowners focus on the visible damage first: missing shingles, water stains on ceilings, broken fencing, or siding torn loose by strong wind. The bigger surprise often comes later, when the insurance estimate arrives and the payout is lower than expected. That gap often comes down to one issue: whether the home was insured for replacement cost or actual cash value. Replacement cost matters because rebuilding after storm damage in Beaumont can be expensive, especially when labor demand rises across Jefferson County after a widespread weather event. Understanding that difference before a claim happens can make a major financial difference.
Storm Risk in Beaumont Creates Higher Rebuilding Pressure
Beaumont homeowners deal with a mix of severe weather risks that make repair costs unpredictable. Wind-driven rain, hail, tropical systems, fallen trees, and extended moisture exposure can all turn a simple repair into a larger restoration project. In Southeast Texas, one storm can affect Beaumont, Port Arthur, Orange, and Nederland at the same time, which means contractors, roofers, and remediation crews get booked quickly. When demand spikes, material prices and labor costs can climb fast. A policy designed around replacement cost is meant to reflect what it actually costs to repair or rebuild with similar materials today, not what the damaged part of the home was worth after years of age and wear.
Replacement Cost and Actual Cash Value Are Not the Same
A common question after storm damage is simple: why did the estimate seem short? The answer often starts with depreciation. Actual cash value usually pays the current value of damaged property after subtracting age, condition, and expected wear. Replacement cost, by contrast, is designed to pay what it costs to replace the damaged item with a comparable new one, subject to policy terms and limits. For example, if an older roof in Beaumont is damaged during a wind event, an actual cash value settlement may reduce the payout heavily because of the roof's age. Replacement cost coverage can reduce the amount the homeowner has to pay out of pocket to restore the roof properly.
The Real Cost Gap Often Shows Up During Roof and Interior Repairs
In Beaumont, storm claims often start with exterior damage but grow once water intrusion is discovered inside the home. A few lifted shingles can lead to damaged roof decking, soaked insulation, stained drywall, warped flooring, and even mold concerns if drying is delayed. If the policy pays on a replacement cost basis, the claim may better align with the actual cost of restoring the home to its pre-loss condition with materials of like kind and quality. If it pays actual cash value, depreciation on older roofing, flooring, cabinets, or other building components can leave the homeowner covering a much larger share. That is why policy language matters long before hurricane season or spring storm season begins.
Policy Limits Matter Just as Much as the Settlement Method
Replacement cost coverage is important, but it does not solve every problem if the dwelling limit is too low. Beaumont homes vary widely in age, square footage, construction style, and upgrade level, and those factors affect rebuilding cost. Brick veneer, custom finishes, updated kitchens, attached garages, and local code requirements can all increase the amount needed after a serious loss. Homeowners sometimes assume market value and reconstruction cost are the same, but they are not. Land value, neighborhood pricing, and housing demand affect market price, while labor, debris removal, permit costs, and material availability affect rebuilding cost. Reviewing limits regularly can help a policy keep pace with real construction conditions in Beaumont and nearby communities.
Why Beaumont and Nearby Communities Need a Local Lens
Local conditions matter when evaluating storm-related home insurance. Homes in Beaumont may face different drainage, tree, roof age, and wind exposure issues than properties in Lumberton, Groves, Bridge City, or Vidor. Older neighborhoods may have aging roofs or outdated materials that are harder to match after a loss. Areas closer to the coast, such as Port Arthur and Orange, may also see heightened concern around wind and water events during tropical weather. Even within Beaumont, homes near heavy tree cover or low-lying spots may experience different claim patterns than homes in newer subdivisions. Replacement cost coverage is most valuable when it is reviewed with the home's actual condition, location, and likely repair environment in mind.
What Homeowners Should Review Before the Next Storm
Key Takeaways
- Confirm whether the dwelling coverage settles losses on a replacement cost basis or an actual cash value basis, because the payout difference after storm damage can be substantial.
- Check the dwelling limit against current rebuilding conditions in Beaumont, including labor demand, material pricing, and any home upgrades completed in recent years.
- Review roof-related provisions carefully, since some policies apply special deductibles, age-based settlements, or separate endorsements for wind and hail losses.
- Document the home's condition with recent photos and keep records of remodels, roof replacements, and major system updates that may support a more accurate claim.
- Ask how ordinance or law coverage works, because repairs after a storm may need to meet current building requirements rather than older construction standards.

Next Steps for Beaumont Homeowners
The best time to understand replacement cost coverage is before a storm claim forces quick decisions. Beaumont homeowners should review their declarations page, dwelling limit, deductible structure, roof settlement terms, and endorsements tied to wind or water-related losses. It also helps to compare how different policies define covered repairs and when withheld depreciation is paid. For homes in Beaumont, Silsbee, Kountze, China, and surrounding Southeast Texas communities, small wording differences can lead to large financial differences after a loss. Comparing coverage carefully and getting updated quote options can help homeowners decide whether their current protection matches today's rebuilding costs and local storm risk.
Compare Coverage Before the Next Storm
Review policy options and quote details now so replacement cost protection is clearer before severe weather hits Beaumont.
Get a Free Quote