Why Other Structures Coverage Matters in Beaumont
Many Beaumont homeowners focus on dwelling coverage and personal property, but detached structures can represent a meaningful part of a property’s value. Other structures coverage, often called Coverage B, usually applies to items not physically attached to the house, such as a fence, storage shed, detached garage, gazebo, or workshop. In Beaumont, that matters because wind, hail, falling trees, and storm debris can damage more than the main home. If a backyard structure needs to be rebuilt after a covered loss, the cost can add up quickly. Understanding how much coverage is enough starts with knowing exactly what is on the property and what it would cost to replace today.
What Counts as an Other Structure
Other structures coverage generally applies to buildings and property features separated from the main house by clear space. In Beaumont, common examples include detached garages used for tools or parking, backyard sheds, privacy fences, carports not attached to the home, and small workshops. Some properties in nearby areas like Lumberton or Kountze may also have larger outbuildings for lawn equipment or hobby use. The key issue is not just whether the structure exists, but whether it would be expensive to rebuild after wind damage, fire, or another covered event. Homeowners should review each detached feature one by one instead of assuming the standard limit will automatically be enough.
How Coverage B Is Usually Calculated
On many homeowners policies, other structures coverage is automatically set as a percentage of the dwelling limit, often around 10 percent. That sounds simple, but it can create gaps. If a Beaumont home is insured for $300,000, a 10 percent limit would provide $30,000 for all detached structures combined. That may be enough for a basic fence and small shed, but it may fall short if the property also includes a detached garage, a long perimeter fence, or custom outdoor improvements. Rebuilding costs in Southeast Texas can rise after major storms because labor and materials become harder to secure. That is why the default percentage should be treated as a starting point, not a final answer.
Estimating the Right Amount for Your Property
A practical way to estimate the right amount is to total the approximate replacement cost of each detached structure. Start with the most expensive item, such as a detached garage, then add fences, sheds, gates, pergolas, and similar features. In Beaumont, even a fence alone can represent a major cost if it runs around a large lot and needs full replacement after wind damage. A detached garage with electrical work, garage doors, and slab repairs can push the number much higher. Homeowners in Orange, Nederland, or Groves with corner lots or larger yards may have more fencing and accessory structures than they realize. A line-by-line estimate gives a much clearer picture than relying on a generic policy percentage.
Local Storm Risk Changes the Math
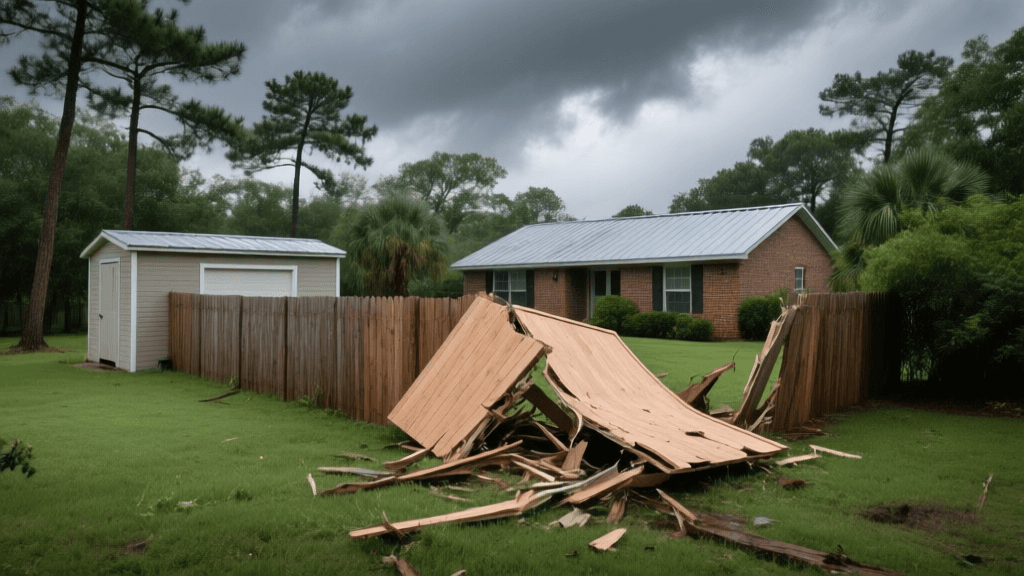
Beaumont homeowners deal with conditions that can be especially hard on detached property. Wind from severe thunderstorms can tear apart fencing panels or damage a lightweight storage building. Hail may dent metal outbuildings or roofing on a detached garage. Saturated ground and falling limbs after heavy rain can also cause losses around the yard. Homes in Port Arthur, Bridge City, and other nearby communities may face similar coastal weather patterns that make exterior structures more vulnerable than people expect. Because these items sit outside and are often built with different materials than the house, they may wear differently over time. That makes it even more important to insure them based on realistic rebuilding costs instead of rough guesswork.
When Standard Limits May Not Be Enough
Standard limits may be too low if the property has multiple detached buildings, upgraded outdoor features, or specialty construction. For example, a homeowner in Beaumont with a detached garage, a workshop, a long wood privacy fence, and a custom gate system could easily exceed a basic Coverage B limit. The same is true for homes in Vidor or Silsbee where larger lots may include more storage buildings or separate utility structures. Another issue is inflation. Materials like lumber, roofing, concrete, and labor can all cost more than expected, especially after a regional storm event. If the estimate for all detached structures is close to the policy limit, increasing coverage may be worth discussing before a claim ever happens.
Beaumont-Specific Property Features to Review
In Beaumont, the right limit often depends on neighborhood layout, lot size, and how the yard is used. Some homes have detached garages behind the main residence, while others have broad fenced yards, separate storage buildings, or covered outdoor spaces used year-round. Homeowners near older neighborhoods may have structures that need higher rebuild budgets because matching materials or updating damaged components can cost more. In surrounding communities like China, Lumberton, and Kountze, larger parcels can mean more fencing and more detached utility buildings. The best review includes measurements, photos, and notes about construction type, roofing, electrical connections, and foundation style so the replacement estimate reflects the property as it actually exists.
Key Takeaways for Beaumont Homeowners
- List every detached structure on the property, including fences, sheds, detached garages, gates, pergolas, and workshops.
- Estimate replacement cost for each item based on current Beaumont-area labor and material pricing, not what was paid years ago.
- Check whether the policy limit for other structures is a percentage of dwelling coverage and compare that number to the total estimated rebuild cost.
- Pay extra attention to storm-exposed features such as long fences, lightweight sheds, and detached garages with their own roof systems.
- Revisit the limit after major upgrades, new construction, or rising building costs in Beaumont and nearby cities.

What to Do Before You Compare Policies
Before comparing home insurance options, gather a basic inventory of detached structures and estimate what it would cost to rebuild them in Beaumont today. Include dimensions, materials, special features, and whether utilities are connected. If there is a detached garage, note door type, roofing material, and any interior finish. For fences, estimate total linear footage and material type. This information makes it much easier to compare policy limits on an apples-to-apples basis rather than choosing based on premium alone. A lower price may not be a better value if other structures coverage is too thin for the property. Taking a little time now can help avoid a much bigger out-of-pocket expense after a covered loss.
Compare Beaumont Home Insurance With Detached Structures in Mind
Review your property features carefully and compare quotes based on realistic other structures coverage, not just the lowest premium.
Get a Free Quote