Why Beaumont Homeowners See Certain Claims Again and Again
Owning a home in Beaumont means preparing for a very specific set of property risks. Southeast Texas weather, heavy rain, humidity, aging plumbing, and fast-moving storms can all turn small maintenance issues into costly insurance claims. Many homeowners are surprised to learn that the most common claims are not always dramatic disasters. A burst pipe under a sink, wind lifting shingles after a thunderstorm, or a visitor slipping on a wet walkway can all trigger a claim. Understanding the patterns behind common losses in Beaumont helps homeowners make smarter coverage choices and reduce the odds of expensive surprises when it is time to file.
The Local Conditions Behind Beaumont Claim Activity
Beaumont homes deal with a climate that is hard on roofs, siding, foundations, and plumbing systems. Long periods of heat and moisture can wear materials down slowly, while tropical weather can cause damage all at once. In neighborhoods across Beaumont, Vidor, and Nederland, homes may also vary widely in age, construction type, and elevation, which affects both claim frequency and repair costs. That local mix matters because insurers look closely at weather exposure, prior losses, and the condition of the property. A homeowner who understands how regional conditions affect insurance risk is in a better position to review deductibles, exclusions, and policy limits before damage happens.
Wind and Hail Damage Often Tops the List
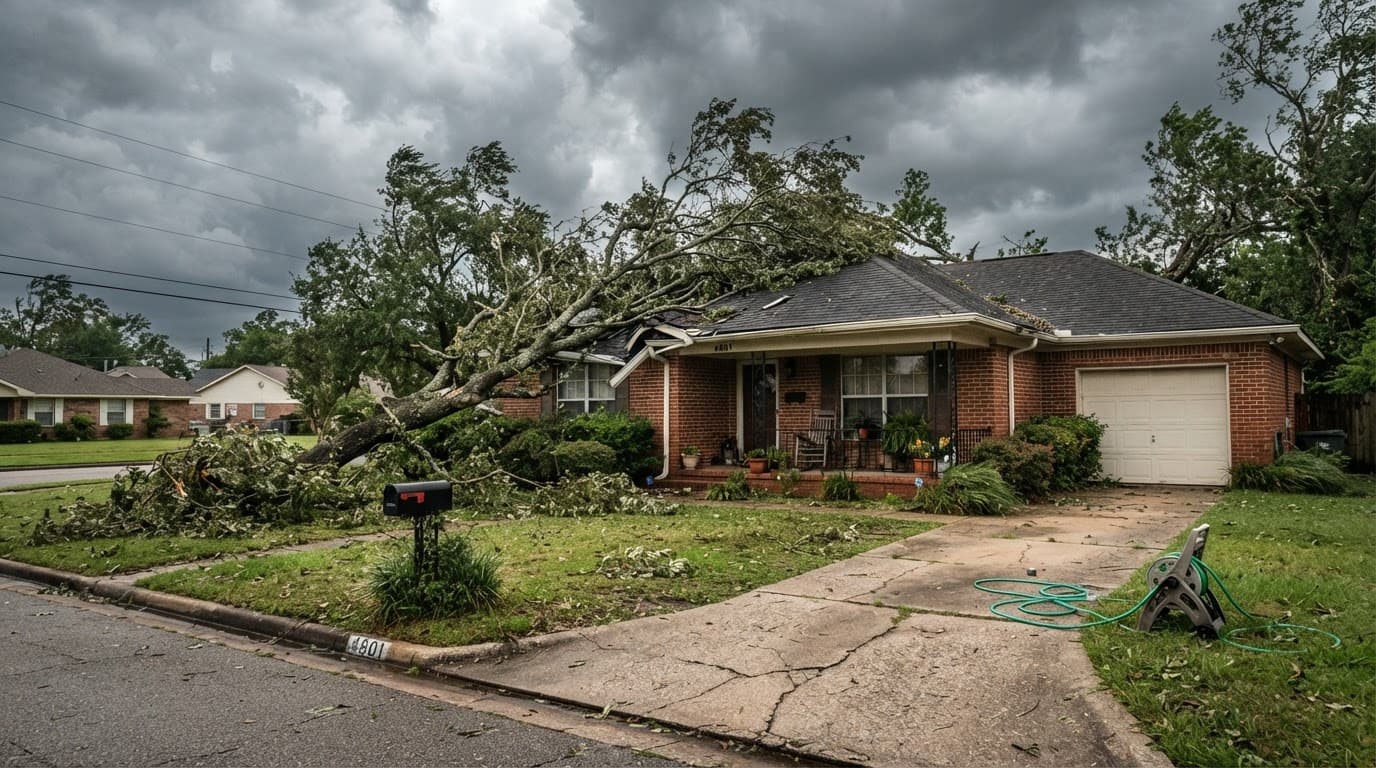
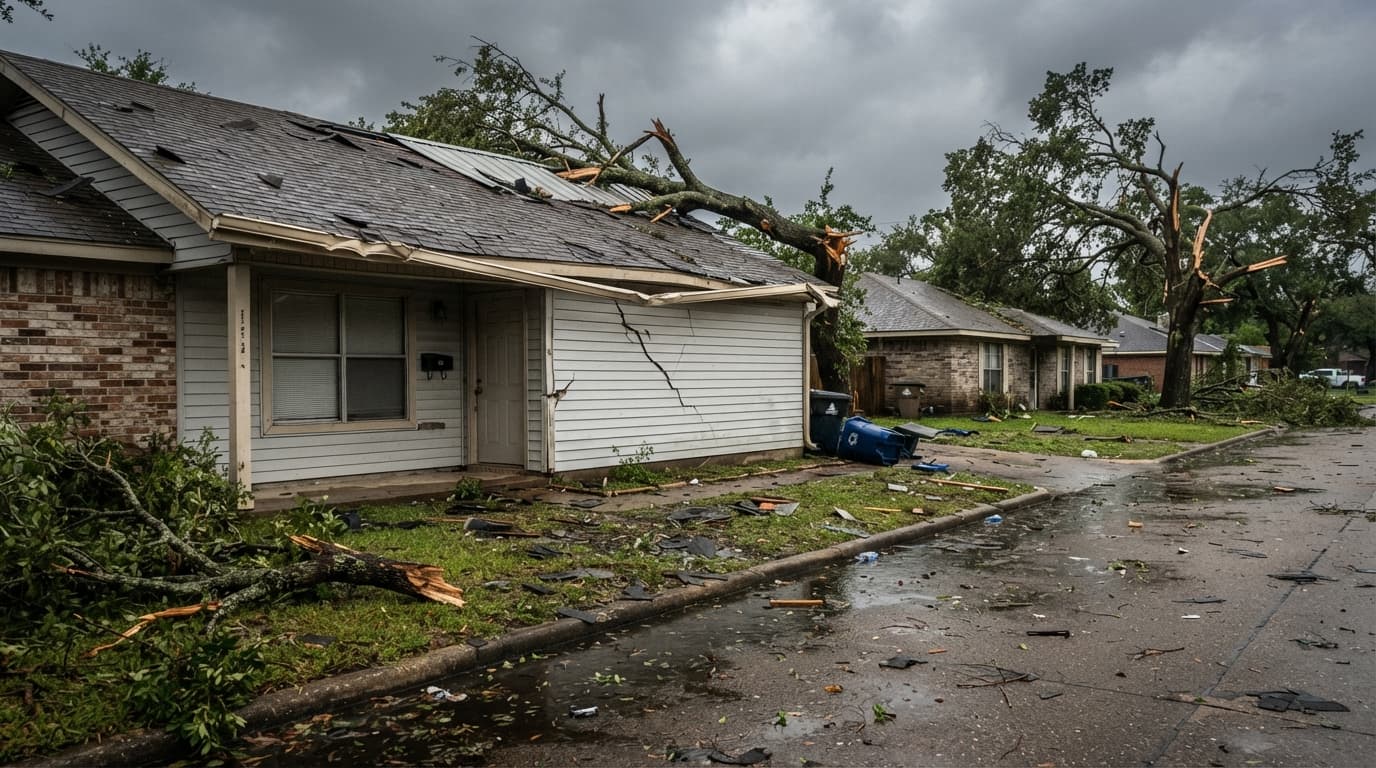
One of the most common home insurance claims in Beaumont involves wind and hail damage. Strong thunderstorms can loosen flashing, tear shingles, crack siding, dent gutters, and send tree limbs onto roofs or fences. Even when the damage seems minor, small openings in roofing materials can allow water intrusion later, which makes quick inspection important. Homeowners should know whether their policy uses a separate wind or hurricane deductible and whether roof settlement is based on replacement cost or actual cash value. After a major storm in Beaumont or nearby Port Arthur and Orange, documenting damage with photos and temporary repairs can make the claims process smoother and reduce disputes over what happened.
Water Damage Claims Come From More Than Flooding
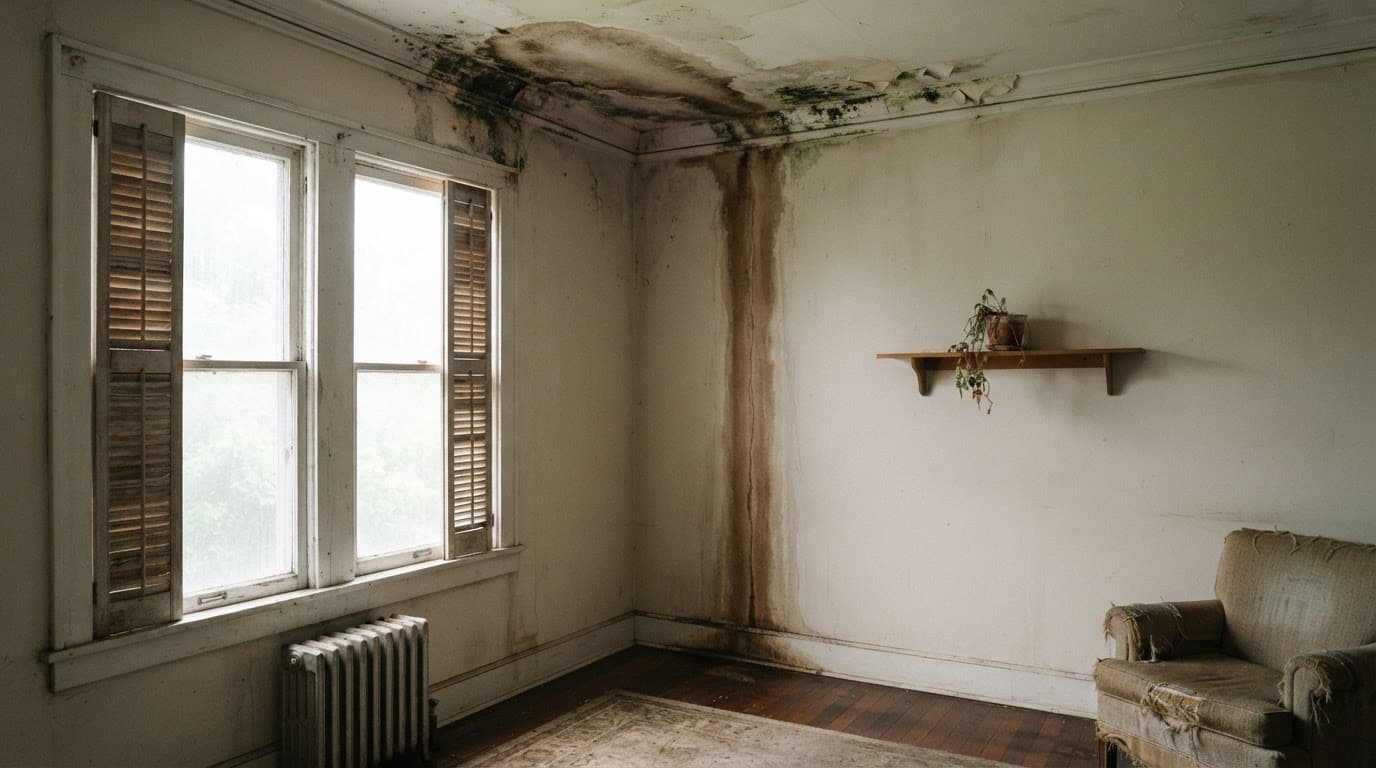
Many homeowners assume water claims only happen during major flooding, but everyday water damage is far more common. In Beaumont, claims often start with leaking supply lines, failed water heaters, clogged drain lines, roof leaks, or washing machine hose breaks. Standard home insurance may cover sudden and accidental internal water damage, but it usually does not cover flood damage from rising water or gradual leaks caused by neglected maintenance. That difference is important in Southeast Texas, where homes can face both storm runoff and indoor plumbing failures. Checking older pipes, replacing worn hoses, and reviewing whether separate flood coverage is needed can prevent one of the most expensive and frustrating claim situations.
Fire and Electrical Losses Still Create Major Costs
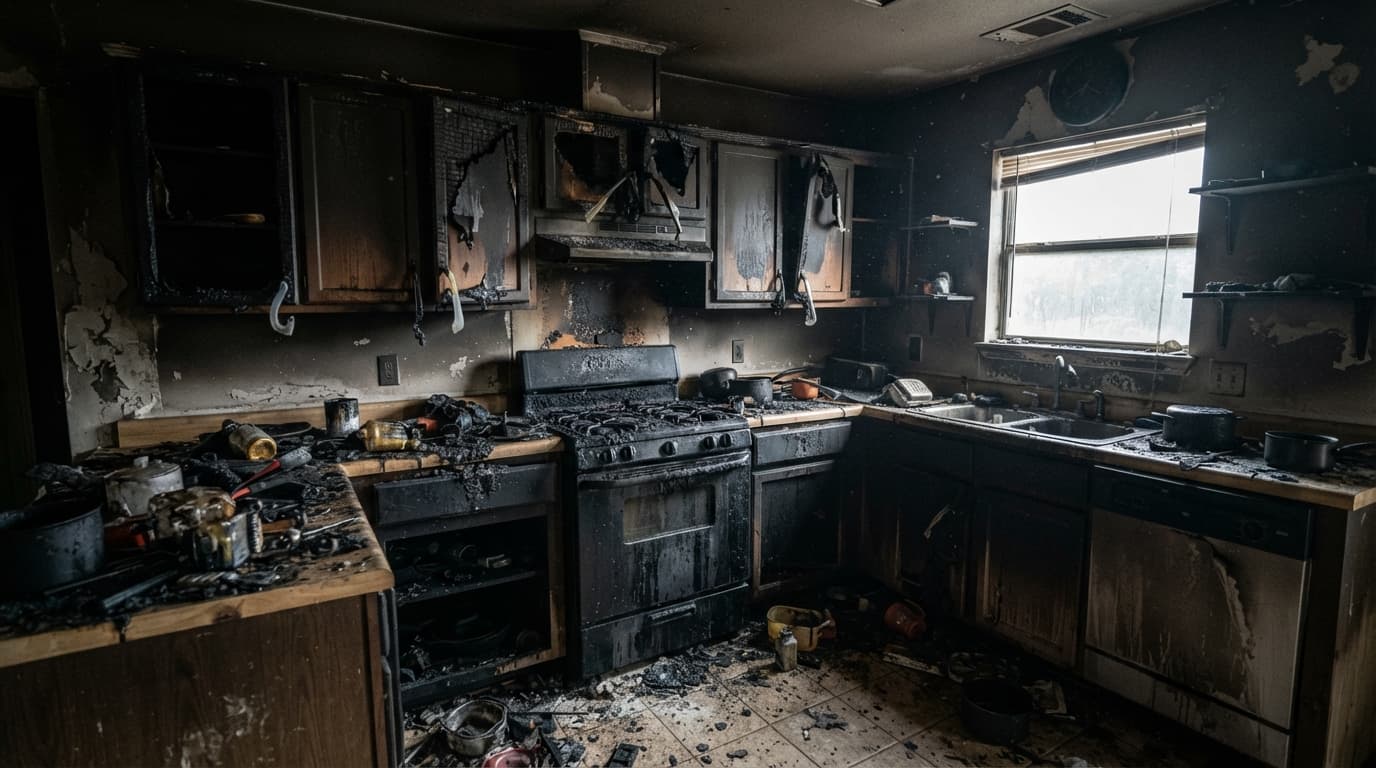
Fire claims are less frequent than some weather or water losses, but they can be among the most severe. In Beaumont, kitchen fires, electrical malfunctions, HVAC issues, and lightning-related surges can cause both direct property damage and smoke damage throughout the house. Older homes in areas around Beaumont, Silsbee, or Kountze may have outdated wiring or panels that increase risk if they have not been upgraded. A small electrical event can damage appliances, electronics, and walls well beyond the original source. Homeowners should review dwelling limits, personal property coverage, and loss-of-use protection so temporary housing and rebuilding costs are not underestimated after a major covered fire event.
Theft, Vandalism, and Liability Claims Are Easy to Overlook
Not every common claim involves weather. Theft and vandalism claims still matter, especially when they involve tools, bicycles, electronics, or damage to doors and windows during a break-in. Liability claims are another area homeowners sometimes overlook until someone gets hurt. A guest tripping over uneven concrete, a dog bite, or an injury around a backyard gathering can lead to medical payments or a larger liability claim. In Beaumont and surrounding communities like Groves, Bridge City, and Lumberton, these claims can happen in ordinary daily life. Reviewing personal property limits, scheduled items, and liability coverage is just as important as preparing for storms or plumbing failures.
Beaumont-Specific Risks That Deserve Extra Attention
Local relevance matters because Beaumont homeowners are not dealing with the same risks as owners in drier or colder parts of Texas. Heavy Gulf moisture can encourage mold after even a brief leak, and strong storm systems can turn routine roof wear into a claim during one bad afternoon. In low-lying areas near drainage channels or neighborhoods with a history of standing water, flood risk deserves separate attention because standard homeowners policies generally do not cover rising water. Homes in Beaumont, Vidor, Orange, and Port Arthur may also face higher claim exposure from wind-driven rain and fallen trees. Local repair costs, contractor demand after storms, and deductible structure all affect how financially disruptive a loss becomes.
Key Takeaways for Beaumont Homeowners
- Wind and hail, non-flood water damage, fire, theft, vandalism, and liability are among the claims homeowners see most often in Beaumont.
- A standard homeowners policy may cover sudden accidental water damage, but flood damage from rising water usually requires separate flood insurance.
- Roof age, plumbing condition, electrical systems, and tree maintenance can all affect both claim likelihood and premium pricing.
- Deductibles matter as much as coverage limits, especially for wind-related losses in Southeast Texas.
- Keeping photos, maintenance records, and a current home inventory can make a future claim faster and easier to support.

What to Do Before You Ever Need to File a Claim
The best time to review home insurance is before any damage occurs. Beaumont homeowners should compare dwelling coverage to current rebuilding costs, confirm whether personal property limits fit what is actually in the home, and understand separate deductibles for wind, hail, or named storms if they apply. It also helps to ask how claims for roof damage, water backup, mold, and detached structures are handled under the policy being considered. A simple annual review, along with photos of the property and a written inventory of valuables, can make a major difference after a loss. Comparing options carefully can help homeowners in Beaumont and nearby communities choose coverage that fits real local risks instead of generic assumptions.